
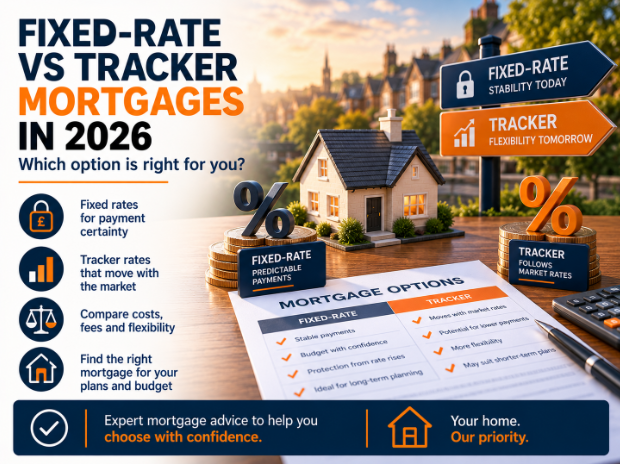
Choosing a mortgage is one of the most important financial decisions a homebuyer or homeowner can make. Among the options available in the UK, fixed-rate and tracker mortgages are two common choices. Both can provide benefits, but they work differently and suit different financial circumstances.
A fixed-rate mortgage offers predictable interest payments for an agreed period. A tracker mortgage usually follows a reference interest rate, meaning the rate you pay can change over time.
Neither option is automatically better. The right choice depends on your budget, financial stability, expectations about interest rates, and willingness to accept uncertainty.
What Is a Fixed-Rate Mortgage?
A fixed-rate mortgage has an interest rate that remains unchanged for a specified period. Common fixed-rate periods include two, three, and five years, although other terms may be available.
During the fixed period, your interest rate does not normally change because of movements in the Bank of England’s Bank Rate. This makes it easier to plan your household budget.
For example, if you take out a mortgage with a fixed interest rate, your scheduled monthly repayment on a standard repayment mortgage will generally remain the same throughout the fixed period, provided the mortgage balance, term, and other relevant conditions remain unchanged.
This predictability can be valuable for households managing rent-to-mortgage transitions, childcare costs, car payments, or other regular expenses.
However, a fixed rate does not guarantee that the mortgage will be the cheapest available option. If market rates fall, you may be unable to benefit from lower rates without paying an early repayment charge to leave your deal.
What Is a Tracker Mortgage?
A tracker mortgage normally follows a reference rate, often the Bank of England’s Bank Rate, plus or minus an agreed percentage.
For example, a tracker might be set at the reference rate plus 1.25 percentage points. If the reference rate rises, the mortgage interest rate would generally rise by the same amount. If the reference rate falls, the mortgage rate may fall as well, subject to the product’s terms.
This arrangement can benefit borrowers when interest rates decrease. However, it also exposes them to the possibility of higher monthly payments if rates increase.
Some tracker mortgages have an early repayment charge, while others offer more flexibility. The product details matter, so borrowers should not assume that every tracker mortgage can be left without a fee.
Comparing Monthly Payments
Consider a hypothetical repayment mortgage of £200,000 over 25 years. The monthly repayment depends on the interest rate and the mortgage structure.
At a lower interest rate, the monthly payment will generally be lower. At a higher rate, more of each payment goes towards interest, increasing the repayment required to clear the mortgage over the agreed term.
With a fixed-rate mortgage, the agreed interest rate remains stable during the fixed period. With a tracker mortgage, payments may change as the reference rate moves.
Before choosing, calculate whether your household could afford a realistic increase in monthly payments. Do not rely exclusively on a forecast that rates will fall.
A mortgage that appears affordable today may become difficult to manage if your income changes or other household costs increase.
The Main Advantages of Fixed Rates
The biggest advantage of a fixed-rate mortgage is certainty. You know the interest rate for the agreed period, which helps you estimate monthly payments and plan other financial commitments.
Fixed rates can be particularly attractive to borrowers who have limited savings or prefer not to take the risk of rising interest rates.
They may also provide reassurance for first-time buyers adjusting to the costs of homeownership. Knowing the main mortgage repayment helps make it easier to budget for insurance, utilities, maintenance, and other expenses.
However, fixed-rate products may have arrangement fees and early repayment charges. If you plan to move home, repay the mortgage early, or make substantial overpayments, review these conditions carefully.
The Main Advantages of Tracker Rates
A tracker mortgage can be attractive if you value the possibility of benefiting from lower interest rates.
If the reference rate falls, your mortgage rate may decrease according to the product terms. This could reduce your monthly payments or the amount of interest you pay over time.
Some tracker products also offer flexible features, although these vary between lenders.
The main drawback is uncertainty. If rates rise, your payments may increase. Borrowers need enough financial flexibility to manage this possibility.
A tracker mortgage may be less suitable for someone whose budget is already stretched or who would struggle to absorb higher monthly repayments.
How Interest Rate Expectations Affect Your Choice
Mortgage rates are influenced by multiple factors, including the Bank Rate, inflation expectations, funding costs, lender competition, and wider economic conditions.
Predictions can be useful when considering different scenarios, but they are not guarantees. Even when financial markets expect rates to fall, economic developments can change those expectations.
Choosing a mortgage based entirely on a prediction can therefore be risky.
Instead, consider what would happen under several possible scenarios. Could you manage if rates stayed where they are? What if they increased? How much could you benefit if they fell?
This approach focuses on your financial resilience rather than attempting to predict the market perfectly. Contact a broker now.
Consider Your Plans for the Property
Your plans can affect which mortgage is appropriate.
If you intend to remain in the property for several years and want predictable payments, a fixed-rate mortgage may suit your preferences.
If you expect to move soon, investigate whether the product can be transferred to another property and what charges may apply. Some mortgages can be ported, but lender approval and affordability checks may still be required.
If you expect to repay a significant portion of your mortgage early, check overpayment allowances and repayment charges. The lowest headline interest rate may not be the best option if it comes with restrictions that conflict with your plans.
Compare the Total Cost, Not Just the Rate
When comparing mortgage products, look beyond the advertised interest rate.
Consider:
- Arrangement or product fees.
- Valuation and legal costs, where applicable.
- Early repayment charges.
- Overpayment allowances.
- The length of the initial deal.
- The rate that applies after the deal ends.
- Portability and other flexibility features.
A mortgage with a slightly higher rate but lower fees may sometimes be more economical, depending on how much you borrow and how long you keep the product.
Use comparable mortgage illustrations and consider the total cost over the period relevant to your decision.
Get Advice Before Making a Decision
A mortgage adviser can help you understand the differences between available products, compare lender criteria, and consider your personal circumstances.
Prestige Mortgage Solutions Ltd may be a useful starting point for borrowers seeking information about mortgage options. Before using any adviser, confirm its regulatory permissions, service scope, fees, and whether the advice is suitable for your needs.
Final Thoughts
Fixed-rate and tracker mortgages serve different priorities. Fixed rates offer payment certainty for an agreed period, while tracker rates provide exposure to changes in a reference rate.
The best choice is not simply the product with the lowest advertised rate. It is the option whose costs, conditions, and risks fit your budget and plans.
Compare the total cost, test your affordability under different interest-rate scenarios, and seek appropriate advice before committing.
This article is for general information only and is not personalised mortgage or financial advice. Product availability, rates, fees, and eligibility depend on individual circumstances and lender criteria.
